

BILL AP & AR Business Payments
4.3

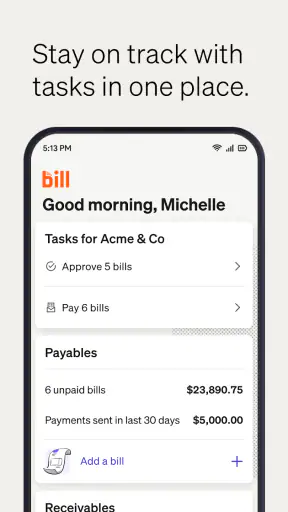
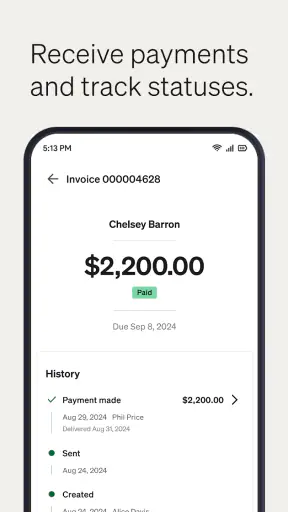
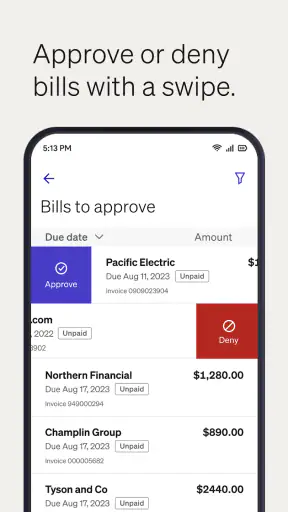
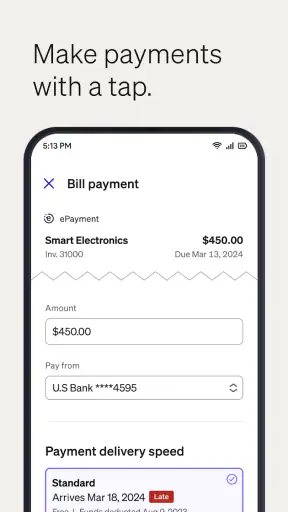
Paying bills and tracking incoming money is rarely difficult because of the payment itself. The harder part is keeping names, amounts, due dates, approvals, and records straight when work is moving quickly. BILL AP & AR Business Payments is built for that practical business problem. I found it most useful as a focused workspace for handling accounts payable and accounts receivable rather than as a general finance app.
The app comes from Bill.com Inc. and sits in the Business category. It is free to download, rated for Everyone, and available for devices running iOS 9 or later. Its current version is 3.7.171, and the app has been around since December 16, 2015. Those details matter less than the workflow, but they help explain what this product is: a long-running business payments tool aimed at people who need more structure than email, paper invoices, or a basic banking app can provide.
My overall impression is that it makes the most sense when several people share responsibility for bills or customer payments. A solo freelancer with a small number of invoices may find a bank app and a spreadsheet quicker. A growing business, however, can benefit from having payment work in one place. The real value is organization around payments, not simply the act of sending money.
How the app feels to read and navigate
A focused business workspace rather than a general finance dashboard
The short description, “BILL AP & AR,” is a good indication of the app’s purpose. I would not open it expecting budgeting tools, personal spending analysis, or a broad accounting education. Its attention is on accounts payable and accounts receivable: money the business needs to send and money it needs to collect.
That narrow focus can help readability. When an app is designed around a defined business task, the user does not have to sift through unrelated personal-finance features. In practice, I found it easier to think in terms of work waiting to be completed: bills to review, payments to manage, and incoming amounts that need attention. This is more useful than a screen filled with decorative charts that do not help me decide what to do next.
There is also a mental advantage to separating business payment work from everyday banking. A bank application usually shows balances and transactions first. BILL AP & AR Business Payments is better understood as a process tool. That distinction is important for owners and staff who need to check the status of a payment, coordinate with another person, or preserve a clearer trail of business activity.
What helps when your attention is limited
Business payment tasks often happen between meetings, calls, deliveries, or customer questions. I appreciate that the app’s purpose can be understood quickly: it is for paying bills and getting paid online. That makes it easier to decide whether it belongs in a particular workflow before investing time in learning it.
My practical advice is to establish a consistent review routine instead of opening the app only when a payment becomes urgent. For example, I would use one short session to review outstanding obligations, another to check incoming payments, and a final check before approving anything significant. This reduces the chance that a rushed glance turns into an accidental approval or a missed item.
The app is also more approachable when the business agrees on simple naming habits. If invoices, vendors, and internal notes are entered inconsistently, no interface can make the records instantly clear. A small team should decide how it identifies suppliers and customer accounts before several months of payment history accumulate. That is an operational tip rather than a flashy feature, but it can make the app substantially easier to use.
Where navigation may demand more concentration
Financial software has an unavoidable precision problem. Amounts, recipients, and payment status cannot be treated casually, so screens may require careful reading even when the layout is clean. I would not describe this as a tool for tapping through without checking. The user needs to slow down at the point where a payment is reviewed or authorized.
That creates a trade-off for people who prefer very simple consumer apps. A banking app may feel faster for a one-off transfer because it is familiar and has fewer business concepts. BILL AP & AR Business Payments becomes more worthwhile when the extra structure prevents confusion between bills owed, money expected, and work already completed.
For a new user, I recommend learning the difference between payable and receivable work before exploring everything else. Mixing those two directions of money is an easy way to misunderstand a screen. I would also avoid beginning with a large backlog. Testing the workflow with a small, clearly understood set of business items gives the team a better chance to notice where labels, review steps, or responsibilities need clarification.
Using it across different abilities and situations
Readability is more than font size
For someone with reduced vision, the important question is not simply whether text can be enlarged. Payment software must make distinctions clear: who is being paid, how much, what the item represents, and whether an action is pending or finished. I found that the app’s usefulness depends on the user being able to inspect those details without relying on memory.
A good personal setup is to work in a quiet environment, increase the device’s text size where it remains comfortable, and avoid reviewing payments while walking or multitasking. I would also keep the device’s display clean and use the brightest comfortable contrast available through the operating system. These steps do not change the app, but they make a meaningful difference when a small visual detail can affect a financial decision.
People with reading difficulties may benefit from handling one payment group at a time instead of scanning a long mixed list. I would begin with the oldest or most urgent items, verify each record against the original invoice, and mark down questions before moving on. Short, repeatable checks are easier to follow than trying to remember several exceptions at once.
For users who rely on spoken feedback or other device-level assistance, the experience will depend partly on how the app exposes its controls to the operating system. I would test the actual screens used for reviewing and approving payments before making it the only tool for a team member. That is especially important because a business workflow can be technically available yet still frustrating if key information is hard to reach with the person’s preferred settings.
Motor effort and the risk of rushed actions
People with limited dexterity may find repeated tapping, scrolling, or precise selection tiring. Payment work is not a good place to reward speed, so I would design the routine around fewer interruptions: sit down, gather the relevant invoices, and complete a small batch rather than opening and closing the app for every item.
A useful safeguard is to separate checking from approving. First confirm the supplier or customer, amount, and reason for the transaction. Then perform the final action only after the information has been reviewed. This two-stage habit reduces the pressure on anyone who has difficulty with quick touch gestures, because the user is not trying to read, decide, and tap correctly all at once.
Users with tremors or other motor challenges should pay attention to how comfortable the app is on their particular device. Larger system controls, a stable surface, and a slower working pace may help. I would not recommend delegating all payment work automatically just because tapping is difficult; a better approach is to give the person a clearly defined review role if that matches their responsibilities and comfort.
Sensory load, hearing, and communication
Business payment tools should not force the user to depend on sound alone. Someone working in a noisy office, a shared space, or a quiet environment may not hear an alert. I would treat any visual status shown in the app as the primary source of truth and use sound only as a reminder when it is available and useful.
People with hearing loss can still participate fully in the payment process when the important information is visible in the workflow rather than communicated only by audio. In a team, written internal instructions are also valuable. A short note explaining who reviews bills, who handles exceptions, and when incoming payments are checked can remove a lot of uncertainty for staff with different communication preferences.
For users who experience cognitive overload, the strongest approach is to reduce the number of decisions made in one session. I would prepare a small checklist: identify the item, compare it with the source document, confirm the amount, check the recipient, and record any question. This is particularly helpful for a business owner who is switching between sales, operations, and payment administration throughout the day.
Working when the normal office setup is unavailable
The mobile format is most useful when payment work cannot wait for a desk. A business owner may be away from the office, a manager may need to review an item during travel, or a small team may divide responsibilities across locations. In those situations, a dedicated mobile workspace can be more practical than waiting to access a computer.
Still, I would distinguish between reviewing and approving. A phone is convenient for checking what needs attention, but a larger screen may be more comfortable when comparing several details or reading a long invoice. My own preference would be to use the mobile app for time-sensitive monitoring and straightforward actions, then reserve complicated exceptions for a calmer session on a larger device or with another reviewer.
Consider a realistic example: a small design studio receives an invoice while its owner is visiting a client. The owner can use the app to see that the bill needs attention, confirm whether it belongs to the studio, and decide whether it should wait for the office administrator. That is more useful than opening a banking app and trying to reconstruct the invoice context from a bare payment screen. The app supports the business process, not just the transfer.
Where the usual alternatives may be better
For a person who sends only a few payments each month, a bank’s business application may be simpler. It is already familiar, and there may be no reason to introduce another payment workspace when there is no shared approval process or recurring administrative burden. A spreadsheet can also be enough for a very small operation that only needs a basic record.
On the other hand, email threads and paper folders become harder to manage as more people participate. They make it difficult to tell which version of an invoice is current, who has reviewed it, or whether a payment is still waiting. This is where BILL AP & AR Business Payments has a clearer purpose than improvised methods.
Accounting software may be a better choice for a company that needs broad bookkeeping, reporting, inventory, payroll, or tax work in the same environment. I would not select this app as a replacement for every financial system. I would select it when payment operations are the specific problem and the business wants a more deliberate way to handle money going out and coming in.
Remaining barriers before a team commits
The biggest barrier is not the download; it is the change in working habits. If invoices continue arriving through scattered channels and no one agrees who is responsible for review, the app cannot solve the underlying confusion. Before adopting it, I would define the handoff between the person who receives a bill, the person who checks it, and the person who authorizes payment.
Another barrier is the seriousness of financial mistakes. A visually clear interface does not remove the need for verification. New users should be cautious with unfamiliar recipients, unusual amounts, and urgent requests. I would never approve an unexpected payment simply because the request looks professional or arrives with pressure attached. The safest workflow includes checking the original business context outside the payment request when something feels unusual.
Small businesses should also consider whether every team member needs the same level of access. A cleaner division of duties can be more inclusive than giving everyone identical responsibilities. Someone who is excellent at spotting invoice discrepancies may not be the person who should perform the final payment action, and someone who works best on a phone may be better suited to monitoring than detailed document comparison.
The app’s audience rating of Everyone makes it broadly approachable from a content perspective, but that should not be confused with being suitable for every work situation. It handles a serious adult responsibility. A junior employee or family member helping with administration still needs clear training and supervision, regardless of how simple the screens appear.
What the numbers suggest about maturity and fit
The app has an average rating of 4.3 from around 7,500 ratings, with roughly 1,500 written reviews. It has passed the 500,000-install mark, which suggests that it is not an obscure experiment. I see that as useful context, but not as proof that it will fit every company’s process. A popular business tool can still feel wrong if its workflow does not match the way a particular team handles approvals.
Its free price also lowers the initial barrier for trying it. I would use that opportunity carefully: install it, test a small internal workflow, and ask whether the people who actually review payments can read and operate it comfortably. The right test is not whether the owner can complete one payment; it is whether the whole team can repeat the process without confusion.
My inclusive verdict for business payment work
I recommend BILL AP & AR Business Payments to small and growing businesses that need a dedicated place to organize bills and incoming payments, especially when more than one person is involved. I like its focused purpose, its mobile usefulness, and the way it encourages users to treat payment work as a process rather than a quick bank transfer.
I would be more cautious for a solo operator with only occasional payments, anyone looking for full accounting software, or a team that has not agreed on responsibilities. In those cases, a bank app, spreadsheet, or broader accounting platform may be less disruptive. The app is not automatically the most accessible choice simply because it is mobile; each user should test text readability, touch accuracy, assistive settings, and the comfort of reviewing financial details on their own device.
After using it, my advice is simple: start small, create a repeatable review checklist, separate monitoring from approval, and choose responsibilities according to each person’s strengths. With that discipline, the app can make business payments easier to follow for people working in different places and with different needs. Its best contribution is a clearer shared routine for money moving through a business.
For readers deciding whether to try it, the answer depends on the problem in front of you. If the problem is scattered payment information and unclear follow-up, this free Business app from Bill.com Inc. is worth exploring. If the problem is comprehensive accounting or a single occasional transfer, I would look elsewhere. That distinction is what makes the app useful: it does one important area of business administration with a clear, practical focus.
4.3
1.54K Reviews
Pros
- Streamlines invoice creation
- tracking
- and payment management in one app.
- Supports faster customer payments through digital billing options.
- Helps organize accounts receivable with clear payment status visibility.
- Reduces manual data entry and the risk of spreadsheet-related errors.
- Useful for businesses needing centralized access to billing information.
Cons
- Some advanced features may require a paid plan or additional setup.
- The interface may feel complex for users unfamiliar with accounting software.
- Integration options can vary depending on your accounting or payment platform.
- Payment processing availability may depend on region and supported currencies.
- Businesses may need to verify security and compliance settings before use.


